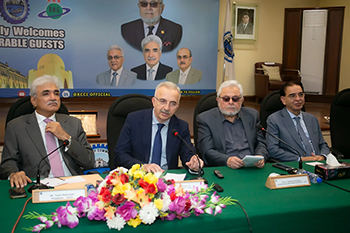
KARACHI: The Institute of Cost and Management Accountants of Pakistan (ICMA), through the 27th issue of its Monetary Policy Statement (MPS) Review, has introduced a scenario-based assessment of the State Bank of Pakistan’s (SBP) latest monetary policy decision, examining not only the rationale behind the policy rate increase but also the potential economic implications of alternative policy choices for businesses, investment, industrial growth and inflation.
Following the SBP’s decision on October 27, 2026, to raise the policy rate by 50 basis points to 12.0%, ICMA’s review goes beyond a conventional assessment of the central bank’s announcement. It compares the actual decision with two alternative scenarios: maintaining the policy rate at 11.5% or reducing it to 10.5%. This comparative analysis examines the potential consequences of each option for inflation, exchange-rate stability, borrowing costs, industrial liquidity and economic recovery, providing a broader perspective on the trade-offs confronting monetary policymakers.
A distinctive feature of this issue is its integration of historical evidence, external economic risk assessment and direct industry perspectives into the monetary policy debate. Drawing comparisons with Pakistan’s monetary policy responses during the Russia–Ukraine conflict in 2022 and the COVID-19 pandemic in 2020, the review explores how geopolitical disruptions, energy prices and domestic supply constraints influence the effectiveness of interest-rate decisions. It also incorporates ICMA’s External Economic Stress Index (EESI) in its ICMA Pre-MP Outlook (released before MPS Review), which declined to -6.12 in August 2026, while cautioning that an improvement in the index does not necessarily mean that external vulnerabilities have subsided.
The review examines the SBP’s decision against a challenging economic backdrop. Headline inflation reached 10.3% in September 2026, while core inflation remained elevated at approximately 8.4%. Meanwhile, large-scale manufacturing recorded year-on-year growth of 1.9% during July–August FY27, indicating a gradual recovery in economic activity. ICMA observes that while monetary tightening may help contain inflation expectations and prevent second-round price increases, it can also raise financing costs for businesses and constrain productive investment. The review therefore emphasizes that monetary policy must be complemented by measures addressing the underlying causes of inflation, including higher energy costs, wheat-supply pressures and supply-chain disruptions.
The review also incorporates insights from industry and sector leaders, highlighting the real-economy implications of monetary policy. Mr. Muhammad Sabir, Principal Economist, SPDC, warned that monetary tightening cannot directly address supply-driven inflation and may constrain economic recovery. Mr. Faisal Sharif, Director, South Asia Region, GAC Group, stressed the need to translate macroeconomic stability into productive investment and export diversification, while Mr. Muhammad Raza, Chairman, REAP, emphasized affordable financing for SMEs and exporters. Mr. Junaid Naqi, Former President, KATI, and Chairman, IMC, and Mr. Hamid Zahur, Former Chairman, Pakistan Tanners Association, highlighted mounting industrial costs, liquidity constraints and competitiveness concerns. Mr. Usman Shaukat, Vice Chairman, PPMA, advocated a gradual transition towards a single-digit policy rate, while Dr. Imran Batada, President, PAFLA, underscored the importance of affordable financing and targeted support for digital exports. Mr. Zulfiqar Alam, CEO, Pakistan Housing Finance Company Limited, cautioned that excessive tightening could undermine investment, employment and economic recovery.
Drawing on its scenario-based analysis and economic indicators, ICMA recommends closely assessing the impact of the policy rate increase on inflation, exchange-rate stability and private-sector credit. The review emphasizes that monetary restraint must be complemented by measures to address energy and food supply pressures, strengthen fiscal discipline and external stability, and reduce financing costs for productive businesses. It underscores the need to balance inflation control with sustainable growth, industrial competitiveness and investment.